About a year before I started tackling my credit card debt, I consolidated six federal student loans into one. I did it for the most boring reason possible: I was tired of tracking three different due dates across two servicers while also budgeting rent and everything else in this city, and I was terrified of accidentally missing a payment because I’d lost track of which loan was due when. What I didn’t expect was that the process itself came with a couple of catches nobody explained to me clearly beforehand.
What I Actually Had
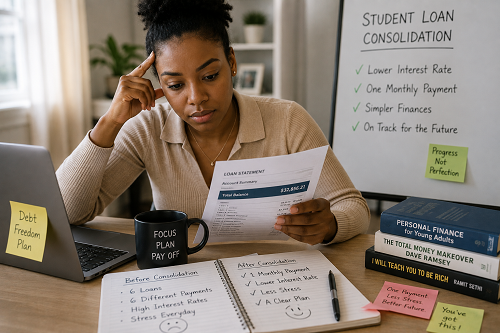
Six loans from four years at a SUNY school, graduating in 2018, totaling $29,400. The rates ranged from about 4.29% up to 6.55% depending on the year they were disbursed, since federal loan rates reset annually and I’d taken out new loans each fall. My blended monthly payment across all of them, on standard 10-year plans, came out to roughly $325.
The Myth I Believed Going In
I assumed, the way a lot of people do, that consolidating would get me a better interest rate — like refinancing a mortgage. It doesn’t work that way with a federal Direct Consolidation Loan. Your new rate is the weighted average of your existing rates, rounded up to the nearest one-eighth of a percent. Not down. Up. My weighted average came out to about 5.79%, which rounded up to 5.875%. So consolidation didn’t save me anything on rate — if anything, it cost me a fraction of a percent versus the true average.
That part I could live with. The part that actually mattered came next.
The Term Length Trap
When I went through the consolidation application, the default option was the Standard Repayment Plan, and because my new balance landed in a certain tier, it defaulted to a 20-year term instead of picking up roughly where my original 10-year plans would have left off. On paper, that looked like good news — my estimated monthly payment dropped from around $325 to about $209.
I almost just took it. A lower monthly number sounds like a win when you’re also budgeting rent in Queens. What stopped me was running the actual total cost both ways before I signed anything. Over 10 years at 5.875%, I’d pay about $9,600 in interest on top of the $29,400. Over the defaulted 20-year term, that interest more than doubled to somewhere around $20,760. Same loan, same rate, just a longer runway — and about $11,000 more out of my pocket for the privilege of a smaller monthly bill.
I went back into the application and manually selected a shorter term to match what I’d already been paying, instead of accepting the default. It’s a real option on the Direct Consolidation Loan application, it’s just not the one that’s pre-selected, and it’s easy to miss if you’re moving quickly.
What I’d Tell Someone Before They Consolidate
Don’t assume consolidation lowers your rate — treat it as a simplification tool, not a savings tool, unless you’re comparing it against a private refinance instead (which trades away federal protections, so that’s its own decision). Actually calculate the total interest cost at whatever term you’re being offered before you accept it, not just the monthly payment, because the monthly number is designed to look appealing and it will. And know that federal loan rules and repayment plan options shift fairly often — mine were accurate when I did this, but I’d double check current terms directly on the Federal Student Aid site before anyone assumes their situation will look identical to mine.
What I Actually Got Out Of It
One servicer. One due date. One login I don’t have to hunt for at 11pm trying to remember if I paid the smaller loan this month or not. That mental load reduction was real and worth doing — I just wish I’d known going in that the “convenient” option and the “cheapest” option weren’t automatically the same choice, and that I’d have to actively pick between them instead of assuming the default was fine.