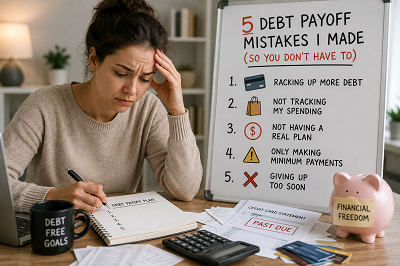
People mostly ask me what worked — how I paid off $15,040 in credit card debt, got my student loans down to one manageable payment, or got a hospital to knock 42% off a bill. Fewer people ask what I got wrong along the way, which is too bad, because the mistakes taught me more than any of the wins did. Here are the five I’d actually flag for someone standing where I was standing.
1. I Told Myself Minimum Payments Counted as “Handling It”
For close to a year before I actually sat down with a spreadsheet, I paid the minimum on all three cards every month and considered that responsible. It wasn’t. When I finally ran the math during paying off my $15,040 in credit card debt, I realized that on my highest-rate card, more than half of every minimum payment was going straight to interest, not touching the actual balance. I wasn’t standing still. I was losing ground slowly enough not to notice.
If you’re only doing minimums right now, it’s worth doing that math once — how much of the payment is interest versus principal — because that number is usually more motivating than any budgeting advice.
2. I Picked a Method and Didn’t Tell a Single Person
I chose my payoff strategy alone, at my kitchen table, and never mentioned the specifics to my roommate or my sister beyond “I’m paying off some credit card debt.” When I explained why I chose the avalanche method over the snowball method to actual friends much later, more than one said they wished I’d told them at the time, because they would have checked in on me during the slow months. Instead, when things got discouraging around month seven, I had no one around to remind me of the math I’d already worked out. I just felt like I was failing quietly, which made an already slow stretch feel worse than the numbers actually were.
Accountability isn’t just for people who need permission to spend less. It’s useful precisely because someone else can hold onto your own reasoning when you temporarily lose track of it yourself.
3. I Didn’t Read the Fine Print Before Consolidating My Loans
When I went through consolidating my student loans, I almost accepted the default repayment term without checking what it meant for total interest, because the lower monthly payment looked appealing in the moment. I caught it that time, but only because I happened to be paying close attention that day. I don’t think that was guaranteed. The real mistake wasn’t the near-miss — it was walking into a decision that size without already knowing what questions I needed to ask before I opened the application.
Anything with a “recommended” or “default” option pre-selected for you is worth treating as a decision someone else made on your behalf, until you’ve confirmed it’s actually the one you want.
4. I Assumed a Medical Bill Was a Fixed Number
For close to two months, I let a hospital bill sit untouched in a drawer because I genuinely believed the number printed on it was non-negotiable, the way a grocery receipt is. It wasn’t until a coworker mentioned she’d gotten her own ER bill reduced that it occurred to me to even try. Negotiating my medical bill down by 42% took about an hour of phone calls total. I’d already spent two months assuming that hour wasn’t worth attempting.
That gap between “this seems fixed” and “this is actually negotiable” cost me nothing in dollars, but it cost two months of a bill hanging over my head that didn’t need to.
5. I Started With Zero Cushion
This is the mistake that connects to all the others. I began my entire payoff plan with no emergency fund at all, which meant every unplanned expense along the way — a dead laptop, anything — felt like a direct threat to the whole plan instead of a manageable bump. I eventually built a small cushion mid-plan, but doing it reactively, under pressure, is a much worse position than doing it first.
If I were starting over, I’d delay the aggressive payoff by even one month to put $500 aside before beginning. It would have made every other mistake on this list less costly when it inevitably happened anyway.
None of these mistakes were disqualifying. I still got to zero. But all five made the process slower, harder, or more stressful than it needed to be, and every one of them was avoidable with information I simply didn’t have yet. If any of these sound familiar, that’s usually the first sign it’s worth fixing before it compounds any further.