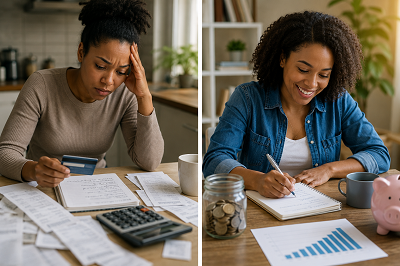
Most people do not have a money problem in the way they think they do.
They have a money management problem.
There is a difference.
Someone earning $3,000 a month can struggle financially, while another person earning $1,500 can steadily build savings, pay bills on time and invest every month. Income matters, of course, but it is only one part of the equation. What happens to the money after it arrives often matters just as much.
That is why money management has become such an important part of personal finance. It is not about being cheap, refusing to enjoy your income or tracking every purchase with a spreadsheet. It is about making deliberate decisions about your money instead of discovering at the end of the month that most of it has disappeared.
What is money management?
Money management is the process of planning, organising and controlling how you earn, spend, save, borrow and invest money.
In everyday terms, it means knowing where your money is going and deciding where you want it to go.
That includes ordinary decisions such as how much to spend on housing, how much to save from each paycheque, whether to pay down a credit card or invest, and how much cash to keep available for emergencies.
Good money management also means looking beyond this month.
You might be able to afford a new phone today, but buying it on credit could make next month’s budget tighter. You might also be earning enough to pay your bills but still have no emergency savings. On the surface, everything looks fine. Financially, however, the situation may be fragile.
This is where money management becomes more than budgeting.
It is about understanding the relationship between today’s decisions and tomorrow’s financial position.
What does money management actually involve?
There are several moving parts, and they affect one another.
1. Managing your income
The obvious starting point is knowing how much money you actually have available.
If you earn a salary, this usually means working with your take-home pay rather than your gross salary. If your income changes from month to month, your approach may need to be more conservative.
A useful question is not simply, “How much do I earn?”
It is:
“How much money can I reliably count on, and when does it arrive?”
That distinction matters when you are planning bills, debt payments and savings.
2. Controlling spending
Spending is where most personal finance advice becomes frustrating because people are often told to “cut unnecessary expenses” without being shown how to distinguish between unnecessary and simply enjoyable spending.
A better approach is to look for spending that does not add enough value to justify its cost.
You may discover that you do not need to eliminate restaurants completely. You may simply be spending more on them than you realised.
The same applies to subscriptions, shopping, convenience fees, transport and impulse purchases.
Money management is not about spending nothing. It is about making sure your spending reflects your priorities.
3. Managing debt
Debt can either be manageable or overwhelming depending on its cost and structure.
A low-interest loan with predictable payments is very different from a credit card balance carrying a high interest rate.
This is why people working on their finances should know the balances, interest rates and minimum payments on their debts.
Once you have that information, you can decide whether the best strategy is to pay the smallest balance first, attack the highest interest rate first, consolidate certain debts or restructure your repayment plan.
Ignoring debt rarely makes it disappear.
What is the 50/30/20 rule of money?
The 50/30/20 rule of money is a popular budgeting framework that divides after-tax income into three broad categories:
50% for needs
30% for wants
20% for savings and debt repayment
So, if your monthly take-home income is $4,000, the framework would suggest approximately:
- $2,000 for necessities
- $1,200 for wants
- $800 for savings and debt repayment
The appeal of the 50/30/20 rule is its simplicity. You do not need to track dozens of categories to understand the basic direction of your money.
But there is a problem with treating it as a law.
Real households are different.
Someone living in an expensive city may spend far more than 50% on housing and basic necessities. A parent supporting several children may have very different priorities from a single professional. Someone carrying expensive credit card debt may reasonably allocate more than 20% towards debt repayment.
So the 50/30/20 rule works best as a starting framework, not a test you can fail.
The more useful question is whether your current spending pattern is sustainable.
If you are consistently spending 70% of your income on essentials, 20% on lifestyle spending and 10% on savings, that is not automatically a bad budget. But it may tell you that your financial margin is smaller than you would like.
What is the best way to manage money?
There is no single answer because the best money management system is one you can actually maintain.
Still, a few principles tend to work across different incomes and lifestyles.
Give every part of your income a purpose
Money becomes easier to manage when it is assigned before it is spent.
That does not mean every dollar needs a category down to the cent. It means you should know how much you need for bills, how much you want to save, how much goes towards debt and how much is available for discretionary spending.
Without that structure, spending tends to become reactive.
Automate important financial decisions
Automation removes some of the need for willpower.
An automatic transfer to savings after payday can be more effective than promising yourself that you will save whatever is left at the end of the month.
The same principle can apply to investments, pension contributions and debt payments.
You are essentially making the decision once and allowing the system to repeat it.
Keep an emergency fund
A financial plan that works only when nothing goes wrong is not a particularly strong financial plan.
Emergency savings give you a buffer against unexpected expenses and income disruptions.
The amount you need depends on your circumstances, but even a modest cash reserve can prevent an unexpected bill from immediately becoming expensive debt.
Know your financial numbers
You do not need to become obsessed with your finances, but you should know a few important numbers.
How much do you spend each month?
How much debt do you have?
What are the interest rates?
How much cash do you have available?
How much are you saving?
What would happen if your income stopped for three months?
These questions are uncomfortable for some people precisely because they expose the gap between feeling financially secure and actually being financially secure.
Money management is not the same as budgeting
People often use the terms interchangeably, but they are not identical.
Budgeting is mainly about planning where your money will go.
Money management is broader. It includes budgeting, saving, debt management, investing, financial planning and making decisions about risk.
Think of budgeting as one tool inside the larger money-management system.
You can have a beautifully organised budget and still make poor financial decisions. For example, you might budget perfectly for monthly expenses while carrying high-interest debt indefinitely.
Likewise, you can manage your money reasonably well without maintaining a detailed spreadsheet.
The quality of your decisions matters more than the complexity of your system.
What’s another word for money management?
Depending on the context, another word for money management could be financial management, financial planning, financial stewardship or personal finance management.
These terms are related, but they are not always interchangeable.
“Budgeting” usually refers specifically to planning income and expenses.
“Financial planning” tends to cover broader long-term decisions, such as retirement, insurance, investments and major financial goals.
“Financial management” can describe the overall process of making and monitoring financial decisions.
For everyday personal finance, money management remains the clearest term because it covers both short-term spending decisions and longer-term financial habits.
Why people struggle with money even when they know what to do
This is where financial advice often misses the point.
Most people already know they should spend less than they earn. They know debt can be expensive. They know saving is important.
Knowledge is rarely the entire problem.
Behaviour is.
Convenience often beats intention. A person may plan to cook at home and still order food after a long day. Someone may intend to save a portion of every paycheque and then find an excuse to spend it.
There is also lifestyle inflation.
When income rises, spending often rises with it. A person who received a raise may feel richer without becoming significantly more financially secure.
The solution is not necessarily greater discipline. It is creating systems that make good decisions easier.
That might mean automatic savings, spending limits, separate accounts for specific goals or removing saved card details from shopping websites.
Small changes in the system can have a larger effect than relying on motivation.
A simple money-management system that works
You do not need an elaborate financial dashboard to get started.
Try this:
Step one: Know your monthly take-home income.
Use the amount that actually reaches your account.
Step two: List your fixed expenses.
Include housing, utilities, transportation, insurance, minimum debt payments and other regular obligations.
Step three: Review your variable spending.
Look at food, shopping, entertainment, subscriptions and other flexible expenses.
Step four: Create a savings target.
Start with an emergency fund if you do not have one.
Step five: Create a debt strategy.
Prioritise expensive debt rather than simply making minimum payments forever.
Step six: Automate what you can.
Set transfers for savings and investments shortly after payday.
Step seven: Review your numbers monthly.
You do not need to rebuild your budget every month. Just check whether reality matches the plan.
This process is simple enough to maintain and detailed enough to reveal where problems are developing.
The goal is not to become obsessed with money
There is a point at which financial management stops being useful and starts becoming exhausting.
The purpose of managing money is not to spend every evening checking transactions. It is to create enough structure that your finances require less attention.
A strong system should give you more freedom, not less.
You should be able to enjoy dinner with friends without wondering whether one meal has destroyed your financial future. You should be able to take a holiday because you planned for it. You should be able to handle an unexpected expense without immediately reaching for a credit card.
That is what good money management ultimately provides: financial breathing room.
You may not control your salary, the economy or every unexpected expense. You can, however, improve what happens to the money that passes through your hands.
And that is where financial progress begins.